Over the past month or so, we’ve seen acquisitions start to pick up in the gold mining and royalty space.
Today, we had news in both the Golden Portfolio and Golden Portfolio 10X services about significant acquisitions.
So far this year, we’ve seen takeover plans for six of our holdings across our portfolios — with one company in our Golden Portfolio service recently announcing plans to buy another.
I can’t yet say whether this is the start of a major merger and acquisition trend.
But what I can tell you is that the majors are focusing on finding value — and as I’ve been pointing out, the whole sector remains undervalued compared to the move in physical gold.
In my paid research, I focus on the highest-quality companies that are trading at the largest discounts to their net asset value. In simple terms, that means I’m looking at gold mining projections years down the line and forming a fair value price based on different scenarios for the gold price. Once you do the detailed analysis, you get a single number: the net asset value (NAV) of the company. You take all the assets, subtract the liabilities, and come up with what the company should be fairly valued at today based on all future production.
If you can buy a dime for a nickel, that’s pretty good. Most of the time, I’m trying to buy a dollar for a dime.
That calculation obviously depends heavily on whether gold is at $2,000, $3,000, or $4,000. My estimates tend to be conservative, so I don’t pin my fair value projections right at the recent all-time highs — I use a lower gold price to provide a margin of safety. Depending on the project, I might use $3,000/oz or even $2,500/oz.
But today, we’re still seeing most of our portfolio holdings valued by the market as if gold were at $2,000 an ounce or lower. Even in official company reports, we typically see estimates based on lower-priced gold — which makes sense.
That’s because mines often take a decade or longer to go from discovery to production. Most of the mines coming online today, or in the near future, were based on business plans that included $1,500 gold — or even lower — which is where gold was a decade ago.
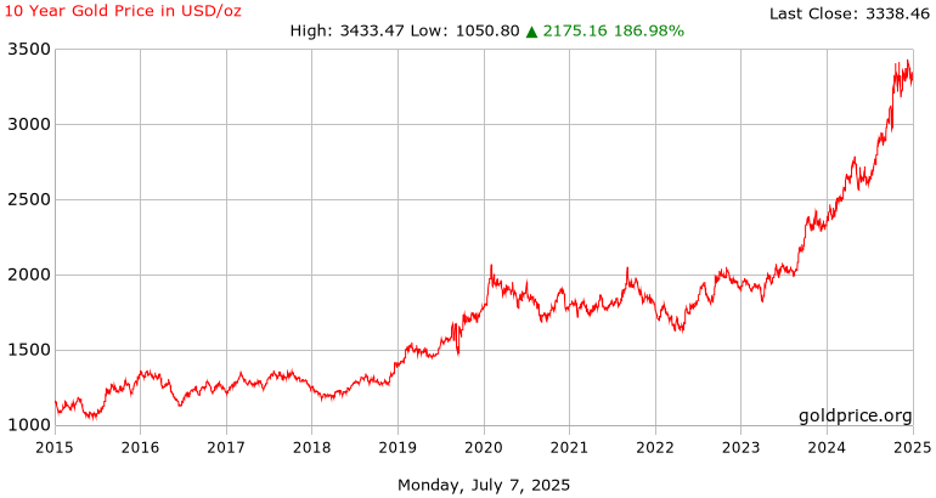
Right now, there’s a massive incentive for gold majors to mine as much gold as they can to take advantage of the economic fact that all of their mines are now producing gold well below the prevailing market price.
They also have a massive incentive to find new gold mines and deals to ensure they have gold to mine in the next decade.
If I can see this massive mispricing in gold stocks, so can gold majors.
All of the gold majors are on a treadmill. They all own mines or gold royalties that have a finite life span. As I frequently say, the best time to own a gold mine is the day before it produces its first ounce. Every day afterwards, the company is sitting on a dwindling asset.
You can see this general trend in a chart I know I’ve posted before:
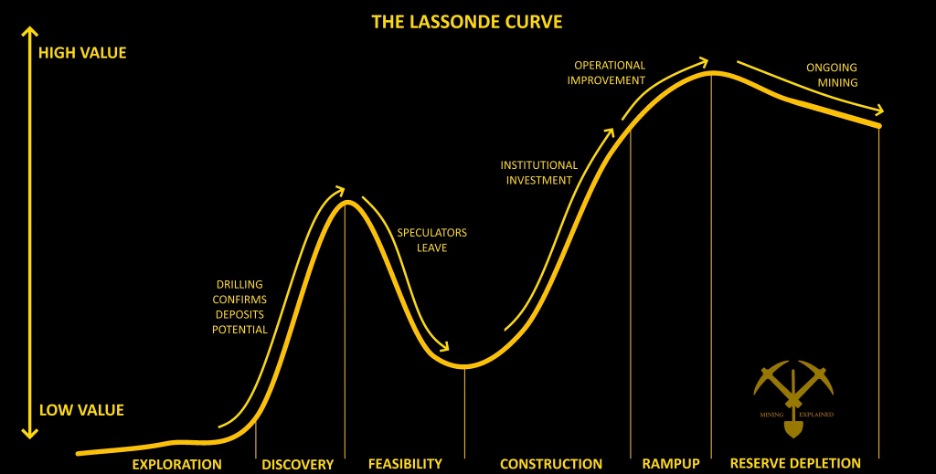
The only way gold majors secure their future is to continually fill the funnel with new gold discoveries and new gold royalty agreements. They need to continually try to drag their overall production to the left on this chart…
And they have two basic ways to fill the funnel:
- They can do their own exploration, development and royalty negotiation.
- They can buy junior gold miners, explorers, developers and royalty firms.
The 2nd method is way easier – and that’s especially true with so many undervalued gold juniors out there…
Seeing this kind of M&A activity at all is a good sign that the industry is healthy and has institutional backing. All of the gold majors have rotating financing with giant investment banks, sovereign wealth funds and other large institutional investors. They would not be making these deals if they didn’t see value in the juniors, or sustained strength in the industry.
I think that’s why we’ve seen a slew of companies in the GP/GP10X lineup start to get acquired. My portfolio is filled with the best deals in the industry.
It’s a little bit of a mixed bag when one of my favorite gold companies gets acquired by a major.
On one hand, we frequently see a nice, short term return. Shareholders don’t tend to accept a takeover if it’s a bad deal.
But on the other hand, some of these companies have a long way to run, and getting acquired means the shares are lumped in with a larger company’s performance. Though I generally suggest taking the shares if there’s a choice between a cash buyout and receiving shares of the acquiring company. We want to retain the upside of the value bought by the larger company unless there’s something really worrying.
My main takeaway: I believe if we continue to see takeovers, the market will start to notice. And we should continue to see our holdings outperform as other investors see the value that gold majors are already seeing.
If that happens, the whole sector could soar – and the smaller companies in my portfolios should absolutely skyrocket.
Best,
Garrett Goggin, CFA, CMT
Lead Analyst and Founder, Golden Portfolio